Region:

How to Calculate Property Yield in Thailand Without Fooling Yourself

Many buyers calculate property yield in Thailand using a flattering shortcut: take the advertised rent, multiply it by 12, and divide it by the purchase price. The problem is that this almost always overstates the result. A realistic yield calculation should distinguish between g…

Category: Investment and yield Region: Thailand Format: Article Reading time: 7 min

EXCLUSIVE SALES LAUNCH · 17 OCTOBER

Exclusive sales · 17 October

KUARTZ & FIZZ — registration is now open

KUARTZ & FIZZ — registration is now open

Two new The Title developments near Karon and Kata beaches. We will shortlist layouts in advance and prepare your application for the sales launch.

By 10:00 AM on 17 October, Phuket time.

Two new The Title developments near Karon and Kata beaches. We will shortlist layouts in advance and prepare your application for the sales launch.

By 10:00 AM on 17 October, Phuket time.

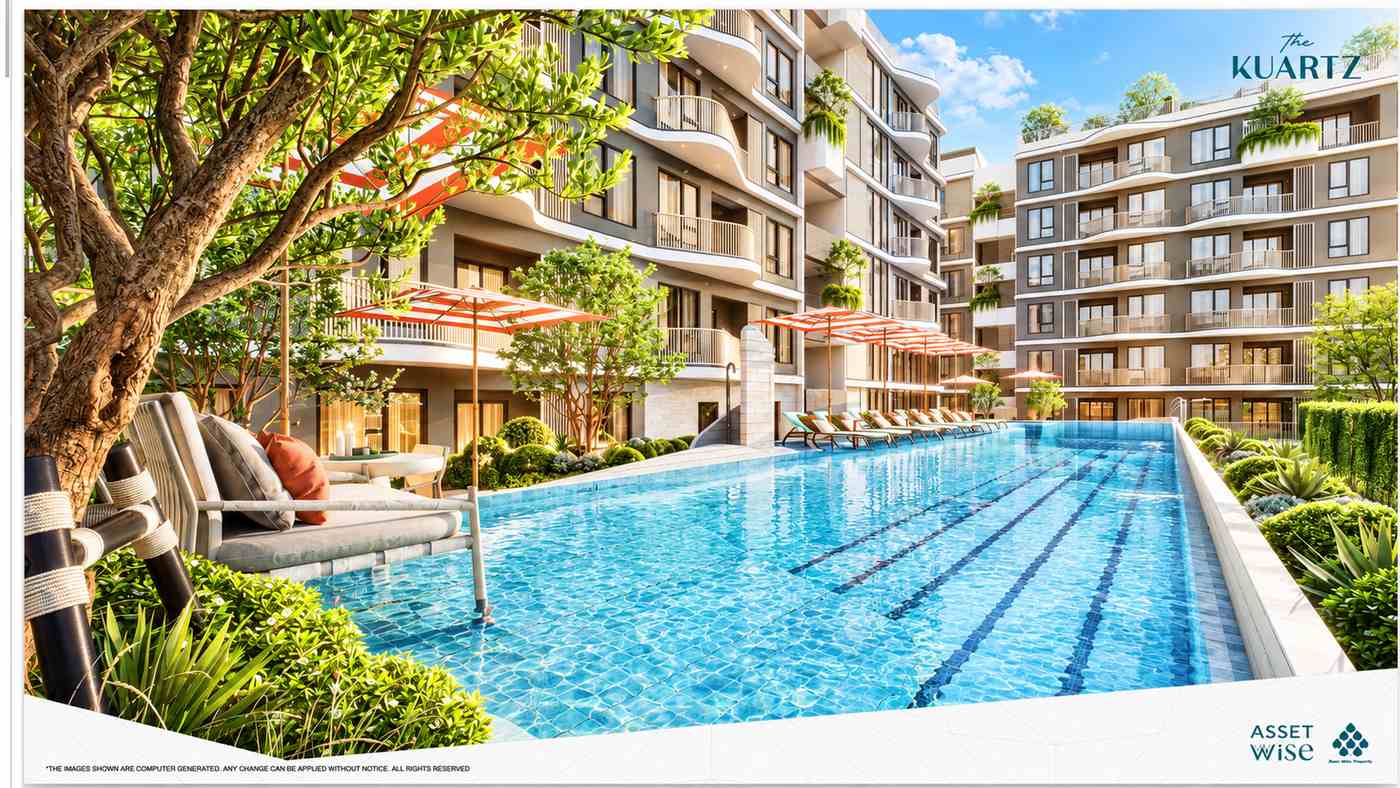
The Title KUARTZ — Condos Near Karon Beach

The Title KUARTZ

Karon · 189 residences 31.7–97.2 m²

from 4 106 000 THB from $121 800 Indicative price
View project →
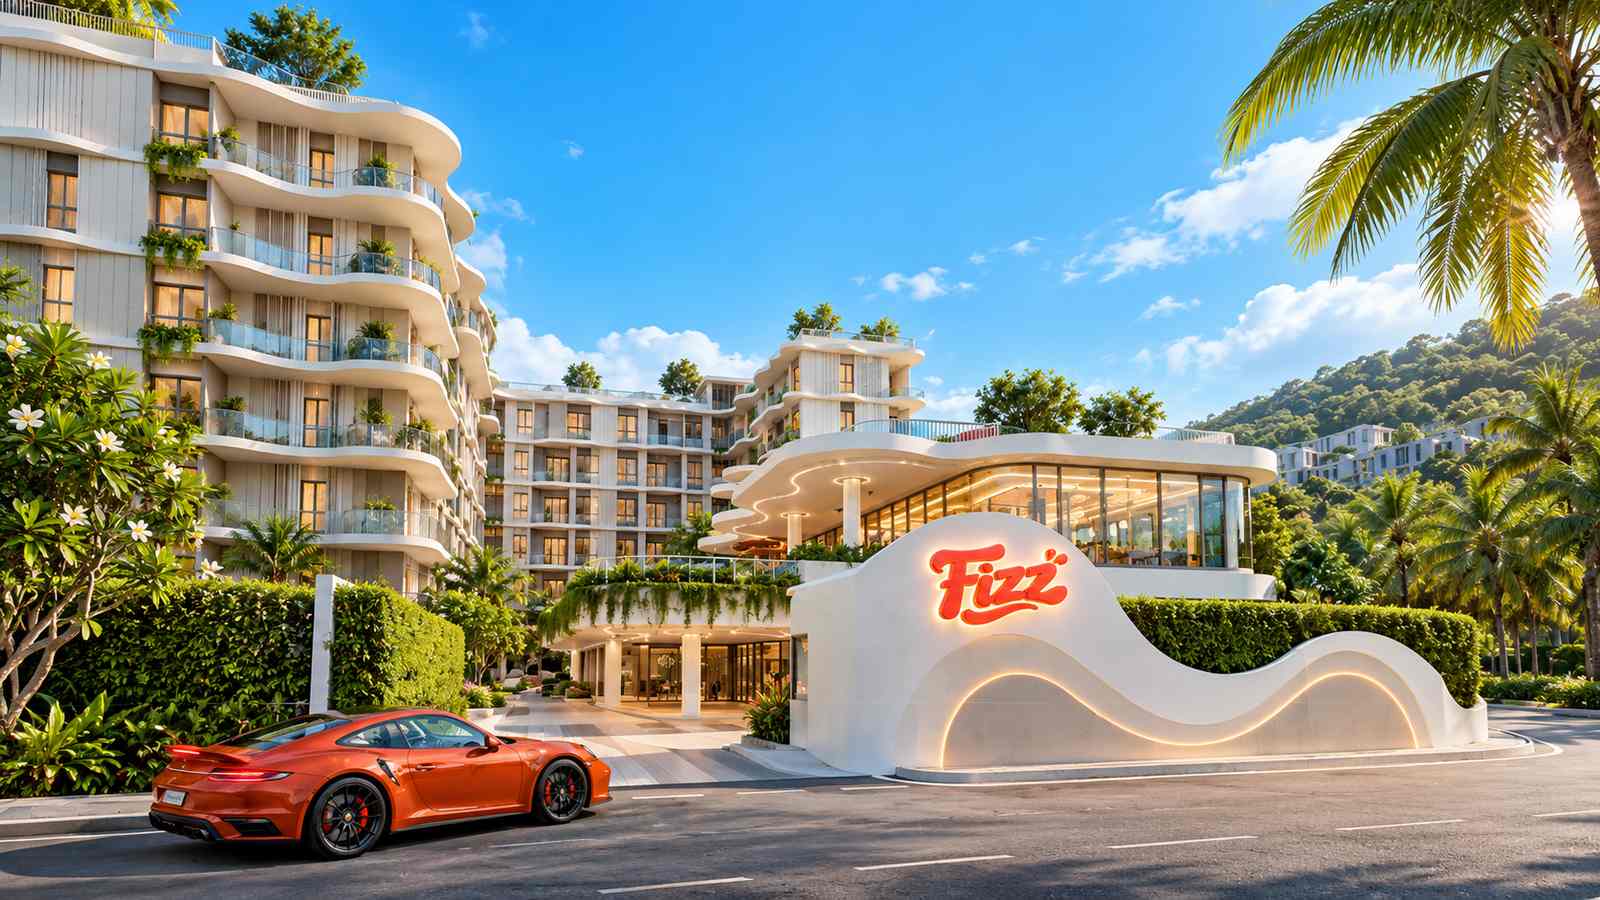
The Title FIZZ Kata — Apartments near Kata Beach, Phuket

The Title FIZZ

Kata · 135 residences 31–110 m²

from 4 010 000 THB from $119 000 Indicative price
View project →

Registration closes in

00 Days
00 Hours
00 Minutes
00 Seconds
How to Calculate Property Yield in Thailand Without Fooling Yourself

How to Calculate Property Yield in Thailand Without Fooling Yourself

When people look at investment property in Thailand, they usually fall for the first nice number they see: “up to 10%”, “guaranteed rental”, or a quick rent × 12 calculation that looks great on paper.

That’s exactly where self-deception tends to start.

The issue isn’t that yield is impossible to calculate. The issue is that it’s often calculated in a way that sells well, but doesn’t hold up when you actually own the unit.

1) Gross yield is only a quick draft

Gross yield = annual rent / purchase price × 100%

It’s a useful first filter, but it ignores everything that matters in real life: costs, vacancy, management, repairs, and the real entry budget.

2) Net yield is the number that matters

Net yield = (annual rent − all annual costs) / total invested capital × 100%

Once you subtract vacancy, management, building fees, minor repairs, furniture refresh, utilities (if owner-paid), taxes, banking costs, and tenant placement, the “headline yield” usually drops fast.

3) The most common mistake: using the wrong base number

People divide by the unit price only. But your real base is total invested capital:
transfer costs, legal fees, bank fees, furniture, appliances, one-off building payments, and setup costs.

If you invested more than the sticker price (and you almost always do), your true yield is lower.

4) Don’t model 12 perfect rental months

Even strong units can sit empty between tenants. Seasons change. Demand moves. A realistic model includes vacancy.

5) Short-term rental looks better on paper, harder in real life

Yes, revenue can be higher — but so are management, cleaning, turnover, marketing, wear and tear, and operational stress. Compare short-term vs long-term by net cash left, not by gross revenue.

6) If it’s not all cash, track what your own cash is earning

If you buy with installments or financing, overall ROI doesn’t tell the full story. It helps to track how much net cash flow your actual cash investment is generating.

7) Don’t mix rental yield and price growth into one “magic number”

Rental income is one story. Price appreciation is another. Until you sell, appreciation is a scenario, not money in your pocket. Keep them separate.

8) A simple no-illusion framework

Use true entry cost, realistic rent, vacancy, all operating costs, and building fees. Then compare gross vs net yield, and also your return on your actual cash invested if the deal isn’t fully cash-funded.

Quick example

A unit that looks like 7%+ on gross can easily become ~4% net once you include real entry costs, vacancy, and operating expenses. That gap is where most disappointment comes from.

Final thought

A pretty yield number is easy to create. A useful one only appears when you stop giving yourself — and the seller — easy assumptions.
Frequently asked questions

It is the basic calculation where annual rent is divided by the purchase price. It is useful as a quick filter, but it usually overstates the real picture because it ignores expenses and vacancy.

Because rental income must be reduced by management, maintenance, vacancy, repairs, common area charges, and other costs. CBRE explicitly explains yield through income versus expenses.

Because it shows the return on your actual invested equity, not on the full property price. This is especially important when the purchase is not fully cash-funded.

No. It may be useful as a starting point, but the real decision should be based on your own model, including your costs, vacancy assumption, and rental strategy.

Hot offers for this topic

from 5 739 000 from $170 300

Sudara Phuket — Residences Near Bang Tao Beach in Phuket

Bang Tao · Phuket

Condo 52–144 sqm 500 m to beach Installment Up to 3 beds Up to 3 baths Q3 2027
View Details
from 3 898 750 from $115 700

Lucean Bay Jomtien Pattaya Wellness Residences

Jomtien · Pattaya

Condo 29.64–130.1 sqm 200 m to beach Installment Up to 3 beds Up to 3 baths Q4 2031
View Details
Featured Hot
from 5 837 000 from $173 200

Canvas Cherngtalay by Sansiri in Phuket

Choeng Thale · Phuket

Condo 39.25–105 sqm 2,300 m to beach Installment Up to 2 beds Up to 2 baths Ready
View Details
from 3 520 000 from $104 400

The Ozone Signature — Condos near Laguna Phuket

Choeng Thale · Phuket

Condo 32–113 sqm 2,000 m to beach Installment Up to 3 beds Up to 3 baths Q1 2027
View Details

Ready to get a shortlist for your goal?

Click the button to open the quick quiz and send your request to live chat.